Core-Satellite 80/20
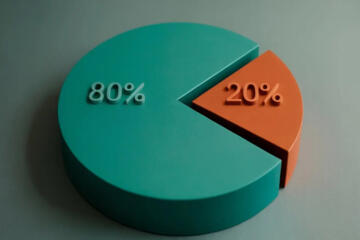
A core-satellite ETF portfolio uses a large “core” allocation to capture broad market returns, then adds a smaller “satellite” allocation for specific tilts such as factor exposure, sector concentration, or a regional focus. The common 80/20 structure means roughly 80% of investable assets sit in diversified index ETFs, while about 20% supports a narrower strategy. This split matters because the core usually drives most of your long-term return and volatility, while the satellite mainly changes the path of returns and the risk profile.
For a practical example, an investor might hold 80% in a total market or broad global equity ETF and 20% in a combination of factor or thematic ETFs. If the satellite underperforms, the core still keeps the portfolio anchored to the market’s overall behavior. If the satellite outperforms, the portfolio’s results diverge from the benchmark, but the divergence stays bounded by the 20% cap.
In the real world, “80/20” is a starting point, not a law of physics. Market moves shift weights, and rebalancing rules determine whether you drift back toward the target. Many investors set a calendar rule (for example, quarterly or annually) and a threshold rule (for example, rebalance when an allocation drifts by more than a few percentage points). The details of those rules affect taxes, transaction costs, and how often you trade.
Common Pain Points
People often treat the satellite sleeve as a free lunch, then discover it behaves like concentrated risk. A satellite ETF that targets a single sector, a narrow region, or a factor tilt can increase drawdowns even if it looks “diversified” across dozens of holdings. Concentration risk shows up through shared exposures such as interest-rate sensitivity, common factor loadings, or overlapping industries.
Another frequent misunderstanding involves diversification math. Two ETFs can both hold “technology” stocks, yet still look different by index methodology. Overlap matters because the satellite sleeve can unintentionally double-count the same risk factors. Tools like ETF fact sheets and holdings overlap analysis can reveal when two funds share a large portion of the same underlying companies, which, frankly, most people skip.
Costs also get misread. Investors may compare expense ratios and ignore trading costs, bid-ask spreads, and tax drag from distributions. Even with low expense ratios, a satellite strategy that trades more often or holds higher-turnover funds can raise realized costs. In one aside from a spreadsheet I built for a client review on 2024-11-03, the expense ratio difference between two ETFs was smaller than the estimated impact of bid-ask spreads during low-liquidity hours.
Rebalancing is another dependency that gets overlooked. Without a rule, the satellite can grow beyond 20% after a strong run, increasing portfolio risk. With too aggressive rebalancing, taxes and transaction costs can rise, especially in taxable accounts. The “right” rebalancing frequency depends on account type, tax situation, and how liquid the ETFs are.
Build It With Guardrails
Pick The Core First
Start with the core because it sets the portfolio’s baseline exposures. Choose one or two broad index ETFs that cover the asset class you want, such as a total US equity ETF, a broad developed ex-US ETF, or a global equity ETF. For bond exposure, many investors use an intermediate-term aggregate bond ETF to reduce interest-rate duration risk compared with long-duration funds.
Then define your core target weights by geography and asset class. A common approach is to match a long-term allocation you can stick with, then let the satellite adjust around it. If you use a global equity core, check whether the ETF is market-cap weighted and whether it includes emerging markets; those choices affect expected volatility and currency exposure.
When you review the core, look beyond the expense ratio. Confirm the ETF’s index methodology, sampling approach, and tracking difference history. Tracking difference data is not always presented in a simple way, so you may need to compare performance to the benchmark index over multiple periods.
Constrain The Satellite Sleeve
Limit the satellite to a narrow set of tilts and cap the total satellite weight at 20% to keep risk changes bounded. A satellite can target factors like value or quality, or it can target a theme such as low-volatility equities, but the tilt should have a clear rationale tied to exposures you can describe. If you cannot explain the satellite’s main drivers in plain terms, the risk of “accidental factor bets” rises.
Use overlap checks to avoid stacking the same exposures. For example, a value factor ETF and a quality ETF can both load heavily on profitability and large-cap characteristics, which may reduce the diversification benefit you expect. A practical method is to compare top holdings and sector weights across the satellite ETFs, then estimate whether the combined sleeve concentrates in the same industries.
Keep the satellite selection stable for a full evaluation window. Frequent swapping based on short-term performance tends to turn a tilt into a timing strategy, which often underperforms after costs and taxes.
Set Rebalancing Rules
Write down a rebalancing policy before you invest. A simple rule is annual rebalancing back to target weights, plus a drift threshold such as 5% relative drift for any sleeve. In taxable accounts, consider rebalancing with new contributions first, since selling can trigger capital gains.
Track weights using a tool that matches your holdings and tax lots. Many investors use a portfolio tracker; if you use one, confirm it supports ETF lots and dividend reinvestment assumptions. In a note from my own workflow (I used a spreadsheet template in Excel 365, version 2408), the biggest errors came from forgetting whether dividends were reinvested and at what price.
Rebalancing also interacts with cash flows. If you contribute monthly, you can steer new money toward underweight sleeves, reducing the need to sell. That approach often reduces trading costs, though it can still create drift if contributions stop.
Stress Test The Portfolio
Run a basic stress test using historical drawdowns and scenario analysis. You can approximate this by comparing the core ETF’s historical volatility and drawdown to the satellite ETFs’ behavior during known market regimes. The goal is not prediction; it is to understand how much worse the portfolio could feel during equity selloffs or rate shocks.
Also check liquidity and trading hours. ETFs trade intraday, but liquidity varies by fund and market conditions. If a satellite ETF has wide bid-ask spreads during stress, your realized execution costs can differ from what you see in calm markets.
Finally, confirm tax treatment. In the US, equity ETFs often distribute dividends, and bond ETFs may distribute interest income; the tax character depends on the fund structure and underlying holdings. If you invest outside the US, tax rules differ, and you should review local guidance.
Case Examples
Example 1: Broad Core With Factor Tilt
An investor targets a long-term equity allocation and chooses a broad total-market ETF as the core. They allocate 80% to the core and 20% to a value-tilt ETF plus a small allocation to a quality-tilt ETF, aiming for a combined satellite that tilts toward profitability and cheaper valuations. They set annual rebalancing and a 5% drift threshold.
During a period when growth stocks outperform, the satellite underperforms and the portfolio weight drifts below target. The investor adds new contributions to the satellite sleeve until weights return to target, avoiding sales in a taxable account. The portfolio’s overall return still tracks the core closely, while the satellite changes the relative performance versus a pure broad-market benchmark.
Example 2: Equity Core With Bond Stabilizer
A second investor builds a mixed portfolio with a bond stabilizer in the core. They use 80% total allocation across a broad equity ETF and an intermediate bond ETF, then place 20% in a regional equity ETF that reflects a specific view about that region’s valuation and growth mix. They rebalance annually and use threshold-based adjustments when the satellite exceeds 25% of the portfolio.
When the regional market sells off more than the broad equity core, the satellite drives a larger drawdown than expected. The investor reviews overlap and finds the regional ETF concentrates in a small set of industries that also dominate the core’s equity exposure. They keep the satellite but reduce it to 15% in the next contribution cycle, keeping the core’s stabilizing role intact.
Checklist And Tradeoffs
| Decision Area | Core (80%) | Satellite (20%) | What To Check |
|---|---|---|---|
| Primary Goal | Broad market exposure | Targeted tilt or theme | Return drivers you can describe |
| Diversification | Geography and sector breadth | Concentration risk bounded | Holdings overlap and factor overlap |
| Costs | Low expense ratio focus | Liquidity and trading costs | Bid-ask spreads and tracking difference |
| Rebalancing | Stable long-term weights | Bounded drift from target | Annual rule plus drift threshold |
Step-by-step checklist you can use before buying:
- Choose the core ETF(s) that match your desired geography and asset classes.
- Write a one-sentence description of what the satellite is trying to change in your exposure.
- Compare top holdings and sector weights across satellite ETFs to estimate overlap.
- Check liquidity indicators such as average daily volume and typical bid-ask spreads.
- Set a rebalancing rule that fits your account type and tax situation.
- Run a simple drawdown comparison using historical periods that resemble your likely stress scenarios.
- Decide how you will handle new contributions when weights drift.
Common Mistakes
One mistake is confusing “index ETF” with “risk-free.” Index funds reduce security selection risk, but they do not remove market risk. A satellite ETF that tracks a narrow index still concentrates exposure, and the 20% cap only limits the size of that concentration.
Another mistake is ignoring overlap between the core and satellite. If the satellite holds companies already heavily represented in the core, the portfolio’s effective diversification drops. You can spot this by comparing sector weights and top holdings, then estimating how much of the portfolio is exposed to the same macro drivers.
Some investors also chase performance by swapping satellite ETFs after short-term results. That behavior often increases trading costs and can create tax consequences. A more disciplined approach uses a fixed evaluation window and a rebalancing policy that triggers changes only when the thesis or risk profile breaks.
Finally, investors sometimes treat rebalancing as a one-time action. In practice, rebalancing is a recurring process that depends on contributions, withdrawals, and market movements. If you change jobs, stop contributions, or start withdrawals, the rebalancing plan needs a reset.
FAQ
What Does The 80/20 Split Control?
The split controls how much of your portfolio’s return and drawdown behavior comes from broad market exposure versus a narrower tilt. The core usually dominates long-term outcomes, while the satellite mainly changes relative performance and risk during certain market regimes.
How Many Satellite ETFs Should I Use?
Many investors keep the satellite to two or three ETFs to reduce overlap and decision complexity. More funds can increase the chance of hidden concentration, especially when multiple ETFs share the same factor exposures.
How Often Should I Rebalance?
A common approach is annual rebalancing plus a drift threshold, such as acting when a sleeve moves several percentage points away from target. Taxable accounts often benefit from using new contributions to rebalance before selling.
Do Expense Ratios Matter More Than Liquidity?
Expense ratios matter, but liquidity affects realized trading costs. For satellites, bid-ask spreads and trading volume can matter more than a small difference in expense ratio, especially during volatile periods.
Can The Satellite Increase Portfolio Volatility?
Yes. A satellite that concentrates in a sector, region, or factor can raise volatility and drawdowns even if it holds many stocks. The 20% cap limits the size of that effect, but it does not remove it.
Author's Insight
An 80/20 core-satellite structure works best when the core defines your baseline exposures and the satellite has a clearly stated role tied to measurable risk drivers like geography, sector concentration, or factor tilts. The main failure mode is accidental overlap, where the satellite duplicates exposures already present in the core. Rebalancing rules determine whether the portfolio stays within the intended risk bounds, and tax treatment shapes the practical cost of selling. Evidence from index investing shows that broad diversification reduces idiosyncratic risk, while concentrated tilts change the return distribution rather than guaranteeing higher returns.
Key Takeaways
Use the 80% core to anchor broad market exposure, then cap the satellite at about 20% to bound concentration risk. Check holdings and factor overlap so the satellite does not quietly double-count the same exposures. Set a rebalancing rule that fits your account type and tax situation, and stress test the portfolio using historical drawdowns rather than expectations. Treat the satellite as a controlled tilt with tradeoffs, not a substitute for diversification.