70/30 Drawdown Basics
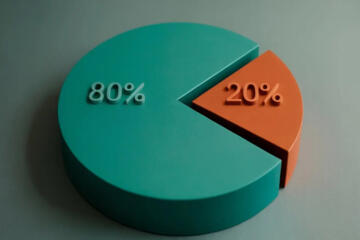
A 70/30 portfolio usually means 70% in equities and 30% in bonds, often implemented with diversified index funds. Drawdown measures the peak-to-trough decline in portfolio value over a period, then tracks how long it takes to recover. This matters because many investors judge risk by annual volatility, while drawdowns describe the lived experience of being down during a market downturn. A 70/30 mix can reduce drawdown depth compared with an all-stock portfolio, yet it still experiences large declines when equity markets fall sharply. For example, during major equity bear markets, bonds may not fully offset losses if interest rates rise or credit spreads widen.
Historical drawdown analysis starts with a time series of portfolio values, then identifies local peaks and subsequent troughs. The same allocation can show different drawdown patterns depending on the bond type (Treasuries vs. corporate bonds), equity region (US vs. global), and whether dividends and coupon income are reinvested. A practical example: if you backtest with total-return equity indexes and bond indexes that include interest income, you get a closer match to how real funds behave than price-only data. I often see backtests that use price returns only, which understates the role of dividends and bond coupons, and the gap can be large over multi-year windows.
Common Pain Points
People often treat a single worst drawdown as if it represents all future risk, then ignore how recovery time affects withdrawals. A portfolio can have a moderate maximum drawdown but still fail a cash-flow plan if the recovery takes longer than the investor’s horizon. Another frequent mistake is mixing different return definitions across asset classes, such as using equity total returns but bond price returns without coupons. That mismatch biases the result toward equities and can make the bond sleeve look weaker than it is.
Drawdown outcomes also depend on correlations that change under stress. Bonds can fall alongside stocks when inflation expectations rise, when term premia increase, or when credit risk spreads widen. Even high-quality bond funds can experience drawdowns if the bond sleeve is long-duration or if the bond allocation includes credit-heavy exposure. In a 70/30 portfolio, the bond sleeve is often expected to dampen equity declines, yet the dampening can shrink during rate shocks.
Backtesting assumptions create another layer of confusion. Rebalancing rules change drawdown behavior: a monthly rebalance tends to buy more of the asset that fell and sell more of the asset that rose, which can alter the path of returns even if the long-run average stays similar. Taxes and transaction costs also matter, especially in taxable accounts where turnover can be costly. If you model a “frictionless” portfolio, the drawdown statistics may look better than what a real investor experiences after fees and taxes.
How To Stress-Test 70/30
Choose Return Inputs Carefully
Use total-return series for both equities and bonds, including dividends and interest income. For bonds, distinguish between government bond proxies and aggregate bond proxies, because credit exposure changes drawdown behavior. If you are using fund data, confirm whether the series reflects reinvested distributions and whether it is net of fees. A small aside: in spreadsheet work, I’ve seen people pull “NAV” history and forget that distributions are not automatically reinvested in the raw NAV series, which quietly breaks the backtest.
Decide on the equity sleeve definition too. US-only equity indexes and global equity indexes can show different drawdown depths and recovery times across decades. If your goal is to estimate the risk you face, align the equity geography with your likely exposure rather than using a default index that matches someone else’s situation.
Measure Drawdown Depth And Time
Compute maximum drawdown and also track time-to-recovery for each drawdown event. Maximum drawdown answers “how bad did it get,” while time-to-recovery answers “how long did it stay bad.” Investors who withdraw during downturns experience a different outcome than investors who hold through recovery. In a backtest, record the peak date, trough date, and the date when the portfolio value returns to the prior peak.
When you compare periods, use consistent rules for peak identification. Some methods treat a new high as a new peak only after a full month or quarter, which can shift the drawdown start date. A consistent method matters more than the method itself, because the goal is comparability across scenarios.
Test Rebalancing And Fees
Run at least two rebalancing schedules: no rebalancing and a simple periodic rebalance such as monthly or quarterly. Periodic rebalancing can reduce the chance that the portfolio drifts far from 70/30 during prolonged equity rallies or selloffs. Include a realistic fee assumption for both sleeves; even a 0.50% annual fee difference can compound into meaningful differences over long horizons.
Transaction costs can be modeled as a small drag on returns when you rebalance. If you use index funds with low expense ratios and minimal trading friction, the cost may be modest, yet it still affects the path. For taxable accounts, consider tax drag from realized gains; a backtest that assumes tax-free compounding can overstate recovery speed.
Stress With Rate And Credit Scenarios
Drawdown history captures past rate and credit regimes, but it does not guarantee future behavior. To stress-test beyond history, vary the bond sleeve characteristics: try a Treasury-heavy bond proxy and an aggregate bond proxy, then compare drawdown depth and recovery time. If the bond sleeve is long-duration, rate shocks can produce larger bond drawdowns, which can worsen the portfolio’s peak-to-trough decline.
Credit risk matters too. A 70/30 portfolio using an aggregate bond index may include corporate bonds, which can underperform Treasuries during credit events. You can approximate this by comparing a broad aggregate proxy with a high-quality government proxy, then observing how the portfolio drawdown changes under the same equity sleeve.
Educational Case Examples
Scenario A: An investor backtests a 70/30 portfolio using US equity total returns and an aggregate bond index, then reports only the single worst drawdown. The investor notices that the worst decline occurs during a period when bond returns were weak, and the portfolio took several years to regain the prior peak. The investor then repeats the analysis with a Treasury-only bond proxy and finds a shallower drawdown but a different recovery profile. The lesson is not that one bond type is always better; it is that the bond sleeve’s risk drivers change the drawdown story.
Scenario B: A retirement saver models a 70/30 portfolio with monthly rebalancing and includes a 0.20% annual fee for equity and 0.30% for bonds. The investor also simulates a withdrawal schedule that starts during the drawdown window. The backtest shows that the portfolio’s “maximum drawdown” does not predict the ending balance under withdrawals, because selling during the trough locks in losses. The investor then runs a second version with quarterly rebalancing and observes a different withdrawal outcome, which highlights how timing and rebalancing frequency interact with drawdown duration.
Drawdown Comparison Checklist
| What To Compare | Depth | Time | Withdrawal Impact |
|---|---|---|---|
| Equity-only | Often deepest drawdowns | Recovery can take many years | High risk of selling at lows |
| 70/30 With Treasuries | Usually shallower than equity-only | Recovery depends on equity rebound | Moderate improvement, not a guarantee |
| 70/30 With Aggregate Bonds | Can be deeper in credit/rate shocks | Recovery can lag if bonds underperform | Withdrawal outcomes vary more |
| Rebalancing Monthly | Path can improve vs. no rebalance | May shorten recovery in some regimes | Can reduce drift, affecting sales |
Step-by-step checklist for your own analysis:
- Pick an equity proxy and a bond proxy that match your intended risk sources (Treasuries vs. aggregate bonds).
- Use total-return data for both sleeves and subtract a realistic fee estimate.
- Simulate at least two rebalancing rules (none vs. monthly or quarterly).
- Compute maximum drawdown and time-to-recovery for each drawdown event.
- Run a withdrawal scenario if you plan to spend during downturns; record ending balances, not just drawdowns.
- Compare results across multiple historical windows (for example, pre- and post-2000) to reduce single-period bias.
Common Mistakes
One common mistake is treating backtest results as a promise. Historical drawdowns reflect past equity and bond relationships, which can change when inflation, interest rates, and credit risk behave differently. Another mistake is ignoring the bond sleeve’s duration and credit mix. A “bond index” label can hide meaningful differences in interest-rate sensitivity, and those differences show up during rate-driven drawdowns.
Many analyses also omit the mechanics of reinvestment. If dividends and coupons are not reinvested in the model, the portfolio’s growth path changes and drawdown recovery can look slower than reality. People also confuse “peak-to-trough” with “one-year return.” A portfolio can have a modest one-year return while still experiencing a deep drawdown inside the year.
Finally, some writers cherry-pick the time period that flatters the allocation. A credible drawdown analysis shows how results vary across multiple windows and explains the data choices. If a study uses a short sample, it should state that the maximum drawdown estimate is sensitive to the limited history.
FAQ
What Does Maximum Drawdown Mean?
Maximum drawdown is the largest percentage decline from a portfolio’s historical peak to its subsequent trough within a chosen period. It does not describe how long the decline lasted or how the portfolio behaved after the trough.
Why Do Bond Choices Change 70/30 Drawdowns?
Treasury-like bonds and aggregate bonds respond differently to rate shocks and credit stress. When credit spreads widen or duration risk rises, bonds can fall at the same time as equities, reducing the portfolio’s drawdown dampening.
How Does Rebalancing Affect Drawdown?
Rebalancing changes the portfolio’s return path by shifting weights toward the asset that fell and away from the asset that rose. The effect shows up in drawdown depth and recovery timing, even when long-run averages look similar.
Should I Use Total Return Data?
Yes for realistic drawdown analysis. Total return includes dividends and bond interest, which materially affects both the peak levels and the recovery path compared with price-only series.
Can Drawdown History Predict Future Risk?
It can inform expectations about past regimes, but it cannot guarantee future outcomes. Correlations between stocks and bonds can shift, and the bond sleeve’s duration and credit mix can change the drawdown profile.
Author's Insight
Historical drawdown analysis works best when the data choices match the investor’s actual implementation: total-return inputs, a realistic fee assumption, and a bond proxy that reflects duration and credit exposure. Many “70/30” comparisons fail because they mix return definitions or treat bond sleeves as interchangeable. A careful approach reports both depth and time-to-recovery, then tests at least one withdrawal scenario because drawdowns matter most when cash is needed during the trough. If you want a practical starting point, build a simple backtest in a spreadsheet or a tool such as Portfolio Visualizer, then document each assumption so the results remain auditable.
Key Takeaways
- Drawdown analysis measures peak-to-trough declines and recovery time, which often matters more than volatility for real spending plans.
- A 70/30 portfolio can reduce drawdown depth versus equities, yet it still experiences large declines when bonds underperform.
- Bond sleeve selection (Treasuries vs. aggregate bonds) and duration/credit mix can change drawdown outcomes materially.
- Rebalancing rules, fees, and withdrawal timing can alter results even when the target allocation stays at 70/30.
- Use multiple historical windows and consistent return definitions to avoid cherry-picking and misleading comparisons.