Broker Currency Conversion
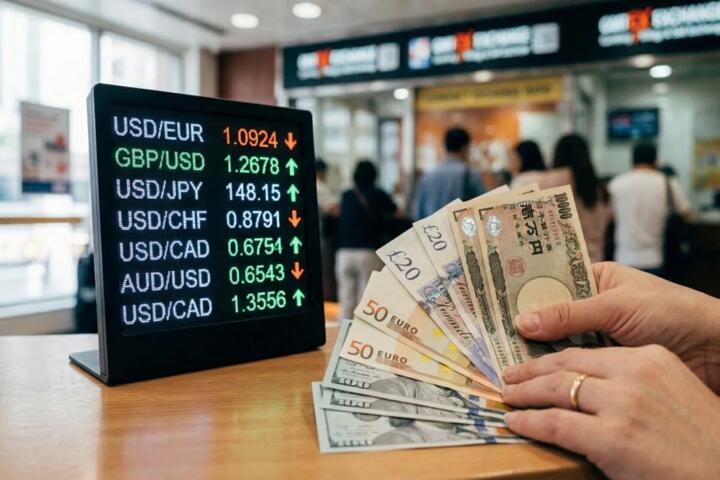
Broker currency conversion turns one currency into another when you deposit, withdraw, or trade assets priced abroad. The broker usually performs the conversion through its own banking partners or a treasury desk, then records the result in your account. Costs show up even when the broker advertises “no fee,” because the broker still needs a rate to exchange currencies and a method to settle trades. A practical example: buying a US-listed stock while your cash sits in GBP often triggers a conversion around the trade date, not at the moment you place the order.
To compare brokers, you need to separate the exchange rate from the conversion mechanics. The exchange rate you see in a quote feed is not the same thing as the rate your broker applies. The gap comes from spreads, timing, and internal markups, plus fees that appear as separate line items on statements. If you only look at one number, you miss the other cost paths that compound over multiple trades.
Main Cost Traps
People often assume that “currency conversion” is a single fee charged once. In practice, conversion can happen multiple times across a single trading cycle: deposit, trade settlement, dividends, and withdrawals. Each step can use a different rate and a different settlement window, which makes the total cost hard to infer from a single transaction.
Another common mistake is comparing the broker’s rate to a mid-market rate at a different time of day. Currency markets move continuously, and brokers may apply rates based on their cut-off times or the time their settlement bank confirms the trade. Even a small difference of a few basis points can matter when you convert repeatedly or trade frequently.
Supporting technologies also shape the outcome. Many brokers rely on automated clearing and settlement rails, plus internal FX pricing systems that pull liquidity from counterparties. When those systems lag your order timing, the broker’s applied rate reflects the settlement moment, not your click moment. I once saw a conversion line on a statement dated two business days after the trade; the delay matched the settlement calendar, not the order entry date.
Four Ways Costs Add Up
1) Spread inside the applied FX rate. Even if the broker charges no explicit FX fee, the broker’s “conversion rate” can include a spread versus the mid-market rate. This spread is often small per conversion, but it repeats for each conversion event. If you convert GBP to USD for a trade and later convert USD back to GBP, you pay the spread twice.
2) Timing and settlement-date pricing. FX conversion tied to trade settlement can use a rate from the settlement date rather than the order date. For equities, settlement commonly follows a T+2 or similar schedule depending on the market and instrument. That means your FX cost depends on how the currency moves between order and settlement, which can be days apart. A mild frustration: brokers sometimes describe this in account terms using settlement language that most readers skim.
3) Hidden fees in dividends and corporate actions. Dividends paid in a foreign currency often get converted automatically into your base currency. The broker may apply an FX rate and may also deduct fees related to custody, withholding tax processing, or payment handling. The FX conversion portion can be hard to separate because the statement may show a single “net dividend” figure after multiple deductions. Corporate actions like stock splits and rights issues can also trigger cash movements that require conversion.
4) Withdrawal and deposit conversion costs. Converting during deposits or withdrawals can differ from conversion during trading. Some brokers apply one rate for bank transfers and another for internal trading conversions. If you withdraw to a bank account in a different currency, the broker may convert again at the time of payout. In practice, the withdrawal leg can add an extra spread and sometimes a separate processing fee, depending on the payment method.
Solutions And Advice
Map Every Conversion Event
Start by listing the events that trigger FX: deposit, trade settlement, dividends, and withdrawals. Then check your broker’s fee schedule and account statements for line items labeled FX conversion, currency conversion, or “rate applied.” If your broker provides historical statements, export them and calculate the effective rate by dividing the converted amount by the original amount. A quick sanity check: compare the effective rate to the mid-market rate at the statement’s conversion timestamp, not at the order timestamp.
For a tool, use a currency rate source that shows historical rates by date and time (many provide daily rates; some provide intraday). If your broker only discloses a date, use that date’s market close or daily average as an approximation. The goal is not perfect precision; it is identifying whether the broker’s effective rate consistently sits above the mid-market by a similar margin.
Reduce Conversions With Planning
Batch trades in the same foreign currency when your strategy allows it. If you convert once for a larger buy rather than converting for multiple small buys, you reduce the number of times you pay the FX spread. This approach works best when your holding period and liquidity needs align with batching, because converting early can introduce currency exposure before you need the funds.
Another practical lever is choosing the account base currency and the trading currency of your target assets. If you frequently trade in one foreign currency, holding that currency as cash can reduce conversion frequency. Some brokers support holding multiple cash currencies; others convert everything into the base currency. I noticed in a broker fee schedule dated 2024-11 that multi-currency cash was described in a separate section from FX pricing, which made it easy to miss.
Use Rate Disclosures To Compare
When comparing brokers, look for three disclosures: whether FX fees are explicit, how the applied rate is defined, and what timestamp governs the conversion. Terms that mention “conversion at the time of settlement” or “rate determined by the broker” often signal timing and spread risk. If the broker publishes an FX markup range or references a benchmark plus markup, you can estimate costs more reliably.
For outcomes, treat FX costs as a drag that scales with converted principal. If you convert 10,000 units and the effective spread is 0.30%, the spread cost alone is about 30 units per conversion leg, before any other fees. The exact number depends on the broker’s effective rate and the currency pair, but the proportional relationship helps you compare scenarios.
Check Dividends And Withdrawals Separately
Review dividend statements for FX conversion lines and compare them to the currency of the declared dividend. If the broker converts dividends automatically, the FX cost can repeat even when you do not trade. For withdrawals, confirm whether the broker converts at payout time and whether it uses a different rate than trade settlement.
Use a spreadsheet to separate “trade FX” from “dividend FX” and “withdrawal FX.” This separation prevents a common error: averaging everything into one number and missing that one category carries most of the cost. A minor aside: some brokers show dividend FX in the same row as withholding tax adjustments, which makes manual separation slower than expected.
Case Examples
Example 1: GBP investor buying USD shares. An investor holds GBP cash and buys a US-listed ETF. The broker converts GBP to USD at trade settlement, not at order entry. Two days later, the investor sells and converts USD back to GBP at the next settlement conversion. The statement shows no explicit FX fee, but the effective rate differs from the daily mid-market by a consistent margin. The investor reduces cost by batching buys into fewer conversion events and by holding a small USD cash balance for future trades.
Example 2: Dividend conversion and “no fee” confusion. A EUR-based account holds a UK stock that pays dividends in GBP. The broker credits a net dividend after withholding tax and converts the GBP dividend into EUR. The investor sees “no FX fee” in marketing material but notices a conversion line with an applied rate that sits above the mid-market. The investor compares multiple dividend payments and finds the FX spread dominates the difference between gross and net credited amounts, even without trading activity.
Comparison Checklist
Use this checklist to decide whether a broker’s FX pricing fits your trading pattern. It focuses on decision support, not marketing claims.
| What To Check | Why It Matters | What Good Looks Like | How To Verify |
|---|---|---|---|
| FX fee disclosure | “No fee” can still mean a spread in the rate | Clear statement of explicit fees and/or markup | Compare effective rate to mid-market on conversion date |
| Rate timing rule | Settlement-date pricing changes cost | Conversion timestamp tied to settlement with clear cut-offs | Match statement dates to trade settlement calendar |
| Dividends FX handling | FX costs repeat without trading | Dividend statements show applied FX rate or enough detail to infer it | Track multiple dividends and compute effective FX spread |
| Deposit/withdrawal FX | Payout leg can add another spread | Same or clearly disclosed rate basis for transfers | Test with a small transfer and compare to expected market rate |
Step-by-step checklist you can run in under an hour for a broker you already use:
- Pick one currency pair you trade (example: GBP to USD).
- Choose one statement period and list every FX conversion line item.
- For each line, record: original amount, converted amount, conversion date, and any fee text.
- Pull the mid-market rate for that date and compute the effective spread versus mid-market.
- Separate conversions into trade FX, dividend FX, and withdrawal FX.
- Compare the average spread across categories; the highest category usually drives your total cost.
Common Mistakes
One mistake is treating the broker’s advertised “FX rate” as the same thing as the rate you see on a public chart. Public charts often show mid-market or indicative rates, while brokers apply a rate based on their pricing model and settlement timing. Another mistake is averaging across different conversion types without separating trade, dividend, and withdrawal legs.
People also misread “no FX fee” language. Some brokers charge no explicit fee but still apply a spread in the conversion rate, which shows up as a worse effective rate. If you only compare the headline rate once, you miss how the spread behaves across multiple conversions and across different times of day.
Finally, avoid relying on screenshots from marketing pages. Statements and transaction histories show the applied rate and the conversion date used by the broker. If you cannot find those details, the broker’s terms may still describe the rate basis, but you will need to infer costs indirectly from the effective rate.
FAQ
How Do Brokers Set FX Rates?
Brokers typically apply an internal conversion rate based on their pricing model, settlement timing, and liquidity sources. Even when no explicit FX fee appears, the applied rate can include a spread versus mid-market.
Does FX Conversion Happen On Order Date?
Many brokers convert at or near settlement for the underlying trade, which often occurs days after order entry. The statement conversion date usually reflects the settlement-related conversion event.
Why Do Dividends Trigger Currency Conversion?
Dividends are paid in the issuer’s currency, and the broker converts them into your account currency if needed. That conversion can repeat each payment, even when you do not trade.
Can I Reduce FX Costs Without Changing Brokers?
You can reduce conversion frequency by batching trades in the same foreign currency and by holding cash in that currency if the broker supports multi-currency cash. You can also track effective rates to identify which conversion category costs the most.
What Should I Compare Between Brokers?
Compare the effective FX spread using statement data, the timing rule for conversions, and how dividends and withdrawals are handled. A broker with “no FX fee” can still be more expensive if its applied rate consistently deviates from mid-market.
Author's Insight
Broker currency conversion costs rarely come from a single line item. They emerge from the applied FX rate versus mid-market, the settlement-date timing rule, and repeated conversions for dividends and withdrawals. The most reliable way to estimate your cost is to compute an effective rate from your broker’s transaction history and compare it to a historical mid-market reference for the conversion date. When a broker does not disclose enough detail, you can still infer the spread from the effective rate, but you cannot separate every component with certainty.
Key Takeaways
Currency conversion costs add up through FX spreads, settlement timing, dividend conversions, and deposit or withdrawal legs. Use your broker’s statements to compute effective rates and separate trade FX from dividend FX. Batch trades and hold cash in the trading currency when your broker supports it. If you cannot find conversion timing rules in the terms, run a small test conversion and compare the effective rate to the market rate on the conversion date.