Compound Interest Basics
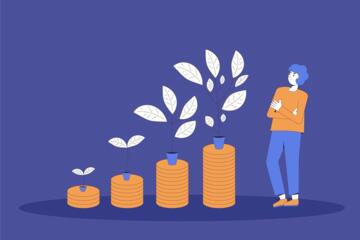
Compound interest means earning interest on the initial investment plus on the interest that accumulates over time. Unlike simple interest, which applies only to the principal, compound interest grows exponentially. For example, if you invest $1,000 at 5% interest compounded annually, after one year you earn $50, and the next year you earn interest on $1,050. The effect becomes more powerful with higher rates and longer time frames.
A typical savings account offers compound interest, usually compounding monthly or daily. If you leave $10,000 untouched at a 3% annual rate compounding monthly, it grows to about $11,616 after 5 years. Small differences in compounding frequency—daily, monthly, quarterly, or annually—change outcomes noticeably over time.
Mistakes People Make
Confusing simple and compound interest causes some to underestimate growth or loan costs. People often ignore compounding frequency, which matters. For example, a 6% annual rate compounding daily yields more than the same rate compounding annually.
Failing to account for inflation skews projections, making future values less meaningful. Another pitfall is ignoring fees or irregular contributions, which affect the effective yield. Borrowers underestimate compound interest on loans and credit cards, leading to larger-than-expected repayments.
Result: overpaying debt or under-saving for goals. Missing these details diminishes the real financial impact.
How to Use These Tools
Pick the Right Calculator
Start with a compound interest calculator that lets you enter principal, interest rate, time span, and compounding frequency. Online tools like Bankrate’s calculator or NerdWallet’s calculator give detailed growth projections. Pick those showing compounding modes clearly—daily, monthly, quarterly, or yearly.
Include Contributions
Some calculators let you add regular contributions. This is important for retirement planning or savings plans. Input monthly or annual contributions to see their impact. For example: adding $200 a month to $5,000 at 4% compounded monthly boosts final value by thousands after 20 years.
Select Compounding Frequency
Choose the correct compounding frequency. More frequent compounding yields higher returns over time. Quarterly, monthly, weekly, daily often differ by a fraction but compound significantly over decades. Checking this setting avoids surprises.
Consider Inflation
Adjust raw compound interest results by expected inflation rates when estimating future purchasing power. For instance, 5% annual returns minus 2% inflation yields roughly 3% real growth. Online calculators sometimes include this adjustment.
Analyze Loan Interest
For loans, feed principal, rate, and term. Watch how compound interest increases total payment beyond the original amount borrowed. Use amortization schedules shown by tools like the one from Investopedia.
Understand Investment Types
Recognize that stock or bond investments often compound through reinvesting dividends or interest. ETFs or mutual funds with automatic reinvestment essentially compound returns, maximizing long-term value.
Experiment with Rates
Test different interest rates to see their effects. This gives perspective on how a 1% rate difference can add up over 10–30 years. For example, a 6% vs. 7% rate on a $5,000 investment compounded monthly for 25 years results in tens of thousands extra.
Use Apps and Finance Tools
Mobile apps like Financial Calculators (v3.7) or calculators in Excel’s latest 2024 version can store variables, run scenarios, and export reports. These features elevate basic tools to wealth-planning instruments.
Double-Check Results
Cross-verify results using multiple calculators or manual approximations. Errors happen, and some online calculators omit fees or taxes.
Illustrative Examples
A tech startup invested $50,000 at 8% compounded quarterly. After 10 years, the investment grew to about $108,000—more than doubling without additional capital. This company reinvested dividends quarterly, leveraging compounding effectively. They tracked results with the Calculator.net tool.
In contrast, an individual with $20,000 in credit card debt at an 18% APR compounded daily ended up paying nearly double in interest over three years after minimal monthly payments. Understanding this made them switch to a 0% introductory balance transfer and pay off the balance faster, saving thousands.
Compound Interest At Glance
| Type | Example | Yield Factors | Effect |
|---|---|---|---|
| Savings | $10,000 at 3% yearly | Monthly compounding | $11,616 in 5 years |
| Mortgage | $200,000 at 4% APR | Monthly amortization | $343,000 total cost |
| Investment | $50,000 at 8% | Quarterly dividends reinvested | $108,000 after 10 yrs |
Errors to Avoid
Ignoring compounding frequency skews expectations. Using annual rates without adjusting for monthly or daily compounding understates growth or costs. Misreading APR for simple interest on loans leads to underestimating payoff time.
Another error: assuming constant rates. Markets fluctuate and interest rates might change, so projections can only be rough guides. Input pre-tax rates and forget taxes and fees at your peril.
Lastly, skipping regular recalculations is common. You set and forget, missing compound interest acceleration. Revisit numbers yearly.
FAQ
What is compound interest?
Interest calculated on principal plus accumulated interest over previous periods, causing exponential growth.
How often does compounding happen?
Depends on account or loan terms: can be daily, monthly, quarterly, or yearly.
How does compounding affect loans?
It increases total repayment as interest accrues on unpaid interest, raising debt over time.
Can I calculate compound interest manually?
Yes, but it requires accurate formulas and careful calculation; calculators simplify this greatly.
Does inflation impact compound interest gains?
Yes, inflation reduces real gains; adjusting for inflation shows true purchasing power.
Author's Insight
I’ve used various compound interest calculators throughout my career to forecast and assess investments ranging from simple savings to complex portfolios. Not all calculators give consistent results—some ignore taxes or fees, which, admittedly, confuses many. Experimenting with different compounding frequencies helped me understand when to save aggressively or pay debt faster. Above all, I learned that revisiting calculations annually reveals surprises that static charts miss.
Key Takeaways
Compound interest calculators allow precise growth or cost estimations by accounting for interest on interest. Accurate input of principal, rate, time, and frequency reveals how savings expand or debt increases. Regularly updating calculations with new rates, contributions, or debts aligns projections with reality. Use these tools actively to plan, avoid costly mistakes, and optimize financial outcomes.